How To Invest In Real Estate: A Beginner's Guide (2026)
Aug 20, 2026
Written by
Alex Martinez — Founder & CEO, Real Estate Skills. Has wholesaled and flipped houses for over 14 years, been part of 1,000+ real estate transactions, and personally acquired 33+ residential investment properties. Has trained 6,000+ investors nationwide.
Reviewed by
Ryan Zomorodi — Co-Founder & COO, Real Estate Skills. Has built a rental portfolio spanning single-family, multifamily, and commercial properties, and reviewed every figure, calculation, and market claim in this guide before publication.
Publication history: Originally published March 3, 2020. Updated August 20, 2026 with corrected 2026 market data, a full rental deal analysis with current-rate underwriting, six real deal breakdowns from Real Estate Skills investors and students, and new sections on deal analysis, market selection, and who this strategy is wrong for. Figures and calculations verified by Ryan Zomorodi, Co-Founder & COO of Real Estate Skills.
Learning how to invest in real estate means putting money into property to earn income, appreciation, or both. Your entry point depends on capital: wholesaling starts near $0, house hacking around $10,000, rentals around $25,000. Pick the strategy that fits your actual position, not the one that sounds best.
Most people asking how to invest in real estate are really asking two quieter questions. Do I have enough money to start? And did I already miss it?
Here's the honest answer to the second one. Everyone spent the start of 2026 predicting rates would come down. They didn't. They hit 5.98% in February, then reversed and climbed all year — 6.67% as of mid-August, the highest point of 2026. Inventory is stuck at 4.6 months and hasn't moved in a year. Prices are still rising, just slowly: $434,100 nationally, up 2%, the 37th straight month of gains. If you read a guide published this spring, including an earlier version of this one, the rate assumptions in it are wrong.
That matters less than you'd think. It changes which deals work, not whether deals work. Our students closed a $4,000 wholesale assignment, bought a $7,000 rental, and finished a $65,000 flip in this market — and you'll see all three broken down line by line, including the mistakes that cost them money.
The first question is easier. You need less than you think, but you need to be honest about which strategy your number actually buys. That's what this guide is built around: what each entry point genuinely costs, which one fits where you're standing right now, and the exact steps from there to your first deal. If you're getting started from scratch, download our free beginner's guide and follow along.
Real Estate Investing For Beginners [ULTIMATE GUIDE]
Alex Martinez walks through how real estate investing actually works — the mechanics, the risks, how it compares to stocks, and the step-by-step process for buying your first rental property.

What Is Real Estate Investing?
Real estate investing means buying property — or the right to buy property — to make money from it. There are four ways it pays: monthly cash flow, appreciation as the property gains value, equity as the loan gets paid down, and profit events like a flip or an assignment fee.
Every real estate strategy makes money through one or more of four levers. Once you can see which levers a strategy pulls, the whole field stops looking like a list of unrelated options.
Cash flow is what's left after the rent comes in and every expense goes out — mortgage, taxes, insurance, maintenance, management. It's your monthly profit. On a Nashville rental our co-founder Ryan Zomorodi bought for $417,000, the rent is $3,300 and every expense adds up to $2,742. That leaves $558 a month. That's cash flow.
Appreciation is the property gaining value over time. You realize it when you sell or refinance. Nationally, prices rose 2% over the past year to a median of $434,100 — the 37th consecutive month of year-over-year increases, though a far cry from the 15–20% jumps of 2020 to 2022.
Equity buildup is the loan balance shrinking. On that same Nashville property, about $350 of every mortgage payment goes to principal — roughly $4,200 in the first year. Ryan didn't pay it. His tenant did, through the rent.
Profit events are one-time payouts at a transaction rather than money arriving monthly. A wholesaler assigns a contract and collects a fee. A flipper renovates and sells. These pay faster and they stop when you stop.
Different strategies pull different levers. A rental investor captures the first three at once. A wholesaler captures only the fourth — but needs almost no capital to do it. A flipper manufactures appreciation through renovation and collects it at sale. A REIT investor gets a slice of appreciation and dividends without ever touching a property.
That's why there's a genuine entry point at almost every income level, and it's why the honest answer to "which strategy is best" is always another question: best for whom, with how much, and how much time?
A definition worth getting right up front: when people say a flip "made $66,000," they usually mean the gross spread between purchase and sale price. That is not profit. It's the number before rehab, financing, carrying costs, and the cost of selling. We'll show you exactly how far apart those two numbers get on a real deal.
The 2026 Real Estate Market: What Actually Happened
Mortgage rates were forecast to fall to around 6.3% in 2026. Instead they bottomed at 5.98% in February, then climbed all year to 6.67% by mid-August — the highest point of 2026. Inventory sits at 4.6 months and prices are still rising slowly.
Every major forecast published at the start of this year said the same thing: rates would drift down through 2026. We said it too, in the March version of this guide.
That's not what happened.
Rates hit 5.98% in February — the low of the year — and then reversed. The U.S. entered a war in Iran in late February, Treasury yields climbed, and mortgage rates followed. By early August the 30-year fixed reached its highest level in a year. It sat at 6.67% on August 13. Fannie Mae now projects roughly 6.4% for the rest of 2026; the Mortgage Bankers Association says 6.5% through year-end. Both are above where the year started, not below.
Here's what that actually costs you. On a $313,000 loan, the difference between 5.5% and 7% is about $305 a month. On a rental with $558 in monthly cash flow, that's most of your profit.
Investment property loans price higher than owner-occupied — typically half a point to a point and a half above — so if primary residences are in the mid-6s, plan on the mid-7s for a rental.
What The Rest Of The Market Looks Like Right Now
| Indicator | Where It Stands | What It Means For You |
|---|---|---|
| Inventory | 4.6 months — unchanged for a year | Still tilts to sellers, but nothing like the 2021 crunch. There's inventory to work with. |
| Median price | $434,100, up 2.0% year over year | 37th straight month of gains — slow and steady, not the 15–20% spikes of 2020–2022. |
| Existing-home sales | 4.06 million annualized | Down 1.7% for the month, up 0.7% for the year. NAR calls activity remarkably stable despite rising rates. |
| Affordability index | 103.3, up from 98.3 a year ago | Improved despite higher rates, because wages outpaced home price growth. |
| Days on market | 29 days, up month over month and year over year | Longer marketing times mean more negotiating room for buyers who can move. |
Figures from the National Association of Realtors, July 2026.
What This Means For How You Invest
The strategies that depend on cheap debt and fast appreciation are harder now. The strategies that don't are largely unaffected.
Wholesaling doesn't care what rates are. You're assigning a contract, not financing a purchase. Our student John collected his first assignment fee in this market without borrowing a dollar.
Flipping is harder, because carrying costs are higher and every extra month on the timeline eats margin. Nationally, gross flipping margins hit their lowest point since mid-2008 in late 2025 before ticking up in the first quarter of 2026 — the first improvement in seven quarters.
Rentals still work, but the math has to be run at today's rate, not last year's. A deal that penciled at 5.5% may not pencil at 7%, and we'll show you exactly how much difference that makes on a real property later in this guide.
The investors getting hurt right now are the ones still running 2021 numbers. The ones doing fine are underwriting to the cost of capital that actually exists.
How Much Money Do You Need To Invest In Real Estate?
It ranges from almost nothing to six figures depending on strategy. Wholesaling can start under $1,000 because you never buy the property. House hacking with an FHA loan runs $10,000–$25,000. A conventional rental typically needs $25,000–$75,000.
Most guides dodge this question. Here's the direct version.
| Strategy | Cash To Start | Hours/Week | Experience |
|---|---|---|---|
| Wholesaling | $0 – $1,000 | 20–30 | Beginner |
| REITs / ETFs | $10 – $1,000 | 1–2 | Beginner |
| Crowdfunding | $500 – $5,000 | 1–3 | Beginner |
| House Hacking | $10,000 – $25,000 | 5–10 | Beginner |
| Fix & Flip | $20,000 – $50,000 | 20–40 | Intermediate |
| Long-Term Rental | $25,000 – $75,000 | 5–10 | Beginner – Intermediate |
| Short-Term Rental | $30,000 – $100,000 | 15–25 | Intermediate |
| Syndication | $25,000 – $100,000 | 2–5 | Intermediate – Advanced |
| Commercial | $50,000 – $250,000+ | 10–25 | Advanced |
What The Table Doesn't Show
Two of these numbers are real, and here's the proof.
John, one of our students in Florida, collected his first wholesale assignment fee without putting up a dollar. His cash buyer covered the earnest money. He'd been in the business three months, working overnight warehouse shifts, and the fee was $4,000. Not life-changing. But it was real money out of a deal that cost him nothing but time.
Days later he bought his first rental — a mobile home in a community 1.8 miles from his house — for $500 down and $6,500 at closing. Seven thousand dollars total, cash, plus about $500 in cosmetic work.
That's the low end of this table, actually happening, in this market.
📍 A Caution On That $7,000 Rental
A mobile home on rented land is not the same asset as a house. It depreciates rather than appreciates, and the lot rent — $769 a month in John's case — can rise without his say. It cash-flows well and it got him started, but don't read $7,000 and assume it applies to single-family homes. Outcomes vary by market, asset type, and terms.
The bigger cost is the one nobody prices. On a flip, you're not just funding purchase and rehab — you're funding the months in between. Our student Savvy's San Jose flip carried six months of hard money interest, roughly $6,000 in property taxes, insurance, and utilities before she saw a dollar. Fifty of those days were lost to an agent who wouldn't do his job, and every one of them cost her interest.
And financing changes these numbers more than most beginners realize. Hard money can fund the purchase and 100% of the rehab. Private money can cover the down payment on top of that. Alex bought and flipped a property on Del Marino Avenue without using any of his own capital by stacking the two. DSCR loans qualify you on the property's rent instead of your tax returns. We cover all of it later in this guide — so don't cross a strategy off this list before you understand what's available.
The one line to take from this table: the question isn't how much do I need. It's which strategy does my number actually buy.
Which Real Estate Strategy Is Right For You?
Match the strategy to your capital and your time, not to what sounds appealing. Under $5,000 and 20+ hours a week points to wholesaling. $10,000–$25,000 with steady income points to house hacking. $25,000+ and limited time points to rentals.
The hardest part of starting isn't picking a strategy. It's picking the right one for where you're standing right now.
Most beginners choose based on what sounds appealing — usually rentals, because passive income sounds like the destination — and then discover they don't have the capital for it. Meanwhile the strategy that actually fits their situation goes unconsidered because it sounds less impressive.
| If This Is You | Start With | Why | Skip For Now |
|---|---|---|---|
| Under $5K, 20+ hrs/week, no experience | Wholesaling | No purchase needed. Builds the deal-finding skill every other strategy depends on. | Flipping, syndications, commercial |
| $10K–$25K, steady W-2, first-time buyer | House hacking | FHA financing drops you to 3.5% down. Rental income offsets the mortgage while you learn to be a landlord. | Short-term rentals, commercial |
| $500–$5K, little time, want exposure | REITs or crowdfunding | Low minimums, no management. Builds familiarity with the asset class. | Wholesaling, flipping |
| $25K–$75K, steady income, want monthly income | Long-term rental | Cash flow plus appreciation plus loan paydown, all at once. Roughly 5–10 hours a week once stabilized. | Commercial, syndications |
| $20K–$50K, some experience, hands-on | Fix and flip | Larger profit per deal. Hard money reduces cash to close. | Passive strategies |
| $25K–$100K, accredited, want truly passive | Syndication | Exposure to large assets with no management. Sponsor due diligence is everything. | Wholesaling, flipping |
The Ladder — And Why It Isn't A Straight Line
The pattern we teach is sequential: wholesale for active income, use that capital to flip for larger profits, then reinvest into rentals for passive income. Each rung funds the next, and each one teaches a skill the next one needs.
Alex ran it in that order. His first wholesale deal was $22,000 on a property he found on the MLS — offered $328,000, contracted at that price, assigned at $350,000, about eight hours of work. Wholesaling taught him how to find deals and, just as usefully, showed him which contractors his cash buyers used and which ones actually delivered. When he did his first flip — Del Marino Avenue, bought at $390,000, $42,000 in renovations, sold for $535,000, about $60,000 profit in 90 days — he already knew where to find the deal and who to hire.
Ryan went the other direction entirely.
📓 From The Field
Ryan bought a rental property first, ran out of cash almost immediately, and then learned to flip and wholesale to refill the tank. He also got licensed so he could earn commissions helping friends and family with their deals. Same destination as Alex, opposite order — which is why we treat the ladder as a default rather than a rule.
So treat the ladder as a default, not a law. If you already have capital and want long-term wealth, start with a rental. If you have time and no money, start with wholesaling. What matters is that you start on a rung you can actually reach.
The failure mode to watch: people get to two or three wholesale deals a month, feel momentum, pile into flips — and stop wholesaling. Then the cash flow that funded everything dries up, because flips only pay when they're finished. Alex's rule is to keep wholesaling continuously and cherry-pick the best deals to flip yourself, wholesaling the rest. Add the next rung; don't trade one for the other.
How To Invest In Real Estate With No Money
Alex Martinez walks through the full progression — wholesaling to fix and flip to rental properties — including two of his own deals and how each strategy funded the next.

You Picked Your Strategy. Here's How To Start Executing It.
Knowing which strategy fits your capital is the first decision. The next one is harder: finding a property whose numbers actually work at today's rates. That's where most beginners stall — not because the math is difficult, but because they've never seen a deal evaluated start to finish.
Our Ultimate Guide walks you through it. How to find discounted properties, what separates a deal worth pursuing from one that only looks good, and the exact steps from where you're standing now to your first offer. It's free, and it's the same roadmap thousands of our students started with.
12 Ways To Invest In Real Estate
The twelve realistic entry points are wholesaling, house hacking, long-term rentals, short-term rentals, fix and flip, BRRRR, REITs, ETFs, crowdfunding, syndications, commercial, and mixed-use. They differ mainly in how much capital and time each demands.
1. Wholesaling
You put a distressed property under contract, then assign that contract to a cash buyer for a fee — without ever buying it. Fees commonly run $5,000 to $25,000. It costs nothing to sign a contract, which is why this is the most accessible entry point that exists. It's also the most active: expect 20–30 hours a week and a lot of rejected offers. Here's how wholesaling works step by step.
Best for: no capital, real time to spend.
2. House Hacking
You buy a property, live in part of it, and rent out the rest — a spare room, a second unit, a converted garage. Because you're an owner-occupant, FHA financing can put you in for 3.5% down instead of the 20–25% an investment property demands. Your tenants offset or erase your housing payment while you learn to be a landlord at low stakes. More on house hacking with an FHA loan.
Best for: $10,000–$25,000, steady W-2, willing to share space.
3. Long-Term Rentals
Buy a property, lease it for a year or more, collect the difference between rent and expenses. This is the strategy that pulls all three passive levers at once — cash flow, appreciation, and tenant-funded loan paydown. Roughly 5–10 hours a month once stabilized, less with a property manager taking 8–10% of rent. Here's our full guide to buying your first rental property.
Best for: $25,000–$75,000, patience, wanting income rather than a project.
4. Short-Term Rentals
Same asset, different operating model: nightly or weekly stays through platforms like Airbnb. Higher revenue potential than a long-term lease, considerably more work — turnovers, messaging, dynamic pricing. The real risk is regulatory. Municipal short-term rental ordinances have tightened sharply since 2022, and a rule change can end the business model on a property you already own.
Best for: $30,000–$100,000, tourist or business-travel markets, tolerance for operations.
5. Fix And Flip
Buy distressed, renovate, sell. Larger profit per deal than wholesaling and far faster than rentals — but you're exposed to rehab overruns, holding costs, and whatever the market does while you're mid-project. In a 6–7% rate environment, every extra month costs real money. Nationally, gross flipping margins bottomed in late 2025 at their lowest since mid-2008 before ticking up in early 2026. Here's how to fix and flip a house.
Best for: $20,000–$50,000, some experience, comfort managing contractors.
6. The BRRRR Method
Buy, rehab, rent, refinance, repeat. You purchase distressed with short-term financing, renovate to raise the appraised value, place a tenant, then cash-out refinance based on the new value and redeploy that capital into the next deal. Powerful when it works. The refinance is the choke point: lenders typically want 620–680 credit, six months of seasoning, and documented rental income — and if the appraisal disappoints, your capital stays trapped. More on the BRRRR method.
Best for: $20,000–$50,000, rehab competence, intent to scale.
7. REITs
Companies that own income-producing real estate and trade like stocks. They're required to distribute at least 90% of taxable income to shareholders, which makes them reliable dividend payers. You can start with the price of one share. You get no leverage, no depreciation, no control — you own a security, not a property. More on real estate investment trusts.
Best for: $10 and up, no time, want exposure without ownership.
8. Real Estate ETFs
Funds holding baskets of REITs and real estate companies. Broader diversification than a single REIT, generally lower fees, fully liquid. Same tradeoff: exposure to the asset class without any of the mechanisms that make direct ownership powerful.
Best for: $10 and up, portfolio diversification.
9. Crowdfunding
Online platforms pooling investor money into specific properties or funds. Minimums often start a few hundred dollars, and unlike a REIT you can usually choose the individual deal. In exchange you accept illiquidity — holding periods run years — plus platform fees and platform risk. More on real estate crowdfunding platforms.
Best for: $500–$5,000, want to pick deals without operating them.
10. Syndications
A sponsor finds and operates a large asset — an apartment complex, say — and investors supply capital for a share of the returns. Genuinely passive, and it gets you into deals no individual could buy alone. Everything depends on the sponsor: their track record, their fee structure, and whether their own money is in the deal. Usually restricted to accredited investors.
Best for: $25,000–$100,000, accredited, want scale without operations.
11. Commercial Real Estate
Office, retail, industrial, and warehouse property leased to businesses. Longer leases mean steadier income, and triple-net structures push maintenance and taxes to the tenant. But you're exposed to business cycles rather than housing demand, valuation works differently, and both capital requirements and management complexity jump considerably. More on investing in commercial real estate.
Best for: $50,000+, business background, portfolio investors.
12. Mixed-Use
Single developments combining residential with retail or office — apartments above storefronts, most classically. Multiple income streams from different tenant types provides some insulation when one sector softens. Financing is harder to secure than residential, and you're effectively managing two different businesses under one roof.
Best for: $50,000+, experienced, wanting diversification within one asset.
Where most beginners actually land: wholesaling if you have time and no money, house hacking if you have a little money and steady income, rentals if you have real capital and want to be relatively hands-off. The other nine are legitimate — they're just rarely the right first move.
How To Start Investing In Real Estate: 9 Steps
Start by assessing your finances honestly, then pick one strategy that matches them. Build your network before you need it, learn to analyze deals, make offers, and expect rejection. Most beginners fail by preparing indefinitely instead of submitting anything.
Step 1: Get Honest About Your Numbers
Pull your credit report and calculate what you can actually deploy without touching your emergency fund.
Credit matters more than beginners expect. A 700+ score gets you the best loan terms; Ryan keeps his at 811 and treats it as a business asset. Below 680, conventional financing gets difficult and expensive — but that doesn't lock you out. It points you toward wholesaling, which requires no loan at all, or hard money, which qualifies you on the deal rather than on you.
Lenders want to see about two years of steady income. If you're self-employed or your income is irregular, look at DSCR loans, which qualify on the property's rent instead of your tax returns.
Then define what you're actually after. Monthly income to replace a paycheck is a different strategy than long-term appreciation. Ryan's rule is to treat your life like a business: know what comes in and what goes out every month. If you can't produce positive cash flow personally, you'll struggle to underwrite it on a property.
Step 2: Pick One Strategy And Commit
Use the selector above. Then stop shopping.
The investors who build portfolios pick one approach, run it until they're competent, and only then add a second. The ones who stay stuck spend two years researching wholesaling, flipping, rentals, and syndications simultaneously and never close anything.
Your first strategy doesn't have to be your last. It has to be one you can execute with what you have right now.
Step 3: Learn Enough To Act — Then Act
There are two failure modes here and they're opposites.
One is jumping in blind. Our student Robert deliberately worked through the entire training before submitting a single offer. His reasoning: he could learn by doing, but he'd make ten times the mistakes, and some of those mistakes kill deals.
The other is preparing forever. Far more people fail this way — consuming videos, building spreadsheets, attending webinars, and never making an offer.
The threshold is the minimum knowledge to execute your chosen strategy competently. Not mastery. Learn how to estimate value, how to run the numbers, and what your contracts say. Then go.
Step 4: Build Your Network Before You Need It
This is the step beginners skip, and it costs them deals.
Two of our students demonstrate it perfectly. Robert lined up three vetted cash buyers before he had a property. When he got one under contract, he sent it to all three, one took it at his price, and he assigned within 72 hours — before his own earnest money was even due. His buyer funded the deposit. Robert never touched his own cash.
Our student Brayden did it in reverse. He found good deals first, then couldn't move them, and kept canceling contracts. He eventually needed a partner to cover his earnest money and had to split his fee.
Same market, same strategy, opposite sequencing, very different outcomes.
📓 From The Field
Robert's hardest-won lesson wasn't about deals — it was that you don't know someone's intentions until there's resistance. A cash buyer who won't answer a text about a live deal is a buyer who vanishes at closing. He now vets on communication as much as on capital.
Whatever your strategy, build the corresponding network first. Wholesaling means cash buyers. Flipping means contractors and lenders. Rentals means agents and property managers. Savvy built her hard money relationship at an online lender meetup and could email at night for a proof-of-funds letter by morning — because she'd done the work in advance.
Step 5: Learn To Analyze A Deal
This is the skill everything else rests on, and it's the one you cannot outsource.
The first agent Ryan worked with brought him a rental she called an excellent investment. He ran the numbers himself and found he'd lose nearly $1,000 every month at her price and terms.
His conclusion, in his words: be a shopper, not just a buyer. Plenty of people will sell you deals for more than they're worth. You are the only person responsible for the math.
We walk through a complete rental analysis, line by line, in the next section.
Step 6: Find Properties
You don't need a marketing budget. Three of the deals in this guide came off the MLS.
Alex's first wholesale deal was an MLS listing he called an agent about. Ryan's Nashville rental was on the market and he paid full price. John's first deal came from an agent who'd started sending him listings.
Two sourcing methods worth knowing beyond the MLS. First, agents who list distressed properties found them somehow — which means they often know about others. Robert called an agent about an on-market listing, that deal fell through on a title issue, and the same agent brought him the off-market property that became his $20,000 deal. Second, look where you already are. John drove past a community daily on his commute, noticed new units going in, stopped, and talked to a man sitting outside who turned out to be the maintenance manager. That conversation became his first rental, and the community now calls him when titles clear.
Wholesaling In Florida: How He Turned His 1st Deal Into A Cash-Flowing Rental
Real Estate Skills student John breaks down his first wholesale assignment and the rental property he bought days later — all while working full-time overnight shifts.

Step 7: Make Offers And Expect Rejection
Brayden targets five to ten written offers a day. Most get rejected. That's the job, not a signal you're failing.
Roughly ten to fifteen written offers produce one deal in our experience — ratios vary by market and offer quality. If you've made four offers and nobody bit, you haven't discovered that this doesn't work. You've discovered that you've made four offers.
Negotiate on more than price. Closing date, inspection period, seller concessions, repair credits, and what stays with the property are all negotiable. Robert won a property over three competing offers partly because he gave the seller a 30-day close so she could clear out her late father's belongings. Terms won that deal, not just the number.
Step 8: Close It
Once under contract, work your due diligence window deliberately. Get a professional inspection. Verify any rental income claims against actual leases and bank statements. Confirm zoning and permit history with the municipality.
Two things that will surprise you. Property taxes usually get reassessed at your purchase price, not the seller's — Savvy paid $900,000 for a property and Santa Clara County assessed it at $1.3 million, producing a $4,000 supplemental bill on top of what she'd already paid. And not every title company is investor-friendly; Robert's nearly killed his assignment at the closing table.
As Alex puts it: time can make all deals happen and kill all deals. Move things forward every day.
Step 9: Know Your Exit Before You Enter
Define at least two exits before you close.
For a rental: sell, 1031 exchange into something larger, refinance and hold, or convert the use if local rules allow. For a flip: retail sale, wholesale it to another investor if the rehab gets away from you, or hold it as a rental if buyer demand softens.
Understand the tax treatment of each before you trigger it. Property held under a year is taxed as ordinary income on the gain; over a year qualifies for long-term capital gains. A 1031 exchange defers gains entirely if you reinvest within IRS timelines — 45 days to identify, 180 days to close. Talk to a CPA before you list, not after you've accepted an offer.
This is educational information, not tax advice. Tax treatment depends on your individual circumstances — confirm with a licensed CPA before making decisions.
How To Analyze A Rental Property
Add up the property's income, subtract every expense including vacancy and management, and what's left is cash flow. Divide annual cash flow by your total cash invested to get cash-on-cash return. Target 8–12%; anything under 4% rarely justifies the capital.
Rental property is valued on the income it produces. More net income, more value. That's the whole principle, and it means your job as a buyer is to figure out what a property will actually produce — not what someone tells you it will.
Two numbers matter most.
Cash flow is income minus expenses. It's the money that reaches your account.
Cash-on-cash return is annual cash flow divided by total cash invested. It tells you whether that cash flow justifies the money you tied up. Invest $100,000 and clear $10,000 a year, that's 10%. Clear $5,000, it's 5%. Below 4% is usually not worth the capital and the work. Eight to 12% is the target band.
How To Analyze A Rental Property (Fast & Simple)
Ryan Zomorodi walks through a complete rental analysis on a property he bought near Nashville — income estimation, every expense line, cash flow, and cash-on-cash return.

A Real Property, Line By Line
Here's a rental Ryan bought near Nashville — new construction, four bed, two and a half bath, about 2,000 square feet. He found it on the MLS, bought directly from the builder at $417,000, and paid full price. He has never seen the property in person.
Income. He didn't guess at rent. He checked active listings with the same bed and bath count in the same neighborhood, adjusted for amenities that actually move rent — in-unit laundry versus on-site versus none, dedicated parking versus street, pet policy — and then called three property managers for their opinions. That gave him a range of $3,000 to $3,300. He underwrote at $3,300 and eventually got it, leasing to the federal government for a military family.
Automated rent estimates on Zillow, Redfin, or Rentometer are a starting point, not an answer. Verify against what's actually on the market right now.
| Expense | Monthly | How He Got It |
|---|---|---|
| Mortgage (P&I) | $1,777 | $313,000 at 5.5% |
| Property taxes | $150 | Local rate × purchase price |
| Insurance | $84 | Quote from a broker |
| Maintenance | $164 | 5% of gross rent |
| HOA | $39 | From the association documents |
| Management | $264 | 8% of gross rent |
| Vacancy | $264 | 8% ≈ one month a year |
| Total expenses | $2,742 |
💡 Running The Numbers On Ryan's Nashville Rental
- Monthly rent of $3,300 minus total expenses of $2,742 leaves $558 in monthly cash flow.
- Annually, that's $6,696.
- Total cash invested was about $110,000 — 25% down plus roughly $6,000 in closing costs.
- $6,696 divided by $110,000 is a 6.1% cash-on-cash return.
Three of those lines deserve explanation. Maintenance at 5% reflects new construction; on a hundred-year-old property Ryan budgets 10–20%. Vacancy at 8% assumes about one month empty a year — tighten to 4% in hot rental markets, loosen to 10% in slow ones. Management at 8% is budgeted even though he self-manages, because he'll eventually delegate it and the deal has to work when he does.
That last habit is the discipline worth copying. Underwrite conservatively. Ryan's actual return is closer to 8–9% because he self-manages and signed a two-year lease that eliminated vacancy — but he bought it assuming he wouldn't.
What Today's Rates Do To That Same Deal
Ryan's 5.5% was a builder incentive, roughly two points below market at the time. That deal closed in a different rate environment than the one you're buying in.
We re-ran his exact numbers at 7%. That's a conservative stand-in — investment property loans typically price half a point to a point and a half above owner-occupied, and with the 30-year fixed at 6.67% in mid-August, a real quote today would likely land higher. The table below is the optimistic version.
| At 5.5% | At 7% | |
|---|---|---|
| Mortgage payment | $1,777 | $2,082 |
| Monthly cash flow | $558 | $253 |
| Annual cash flow | $6,696 | $3,036 |
| Cash-on-cash return | 6.1% | 2.8% |
Same property. Same rent. Same expenses. One and a half points of interest, and the return falls by more than half — from acceptable to not worth doing.
This is the single most important thing to understand about investing in 2026. It isn't that deals stopped working. It's that a deal analyzed at last year's cost of capital tells you nothing about whether it works at this year's. Run your numbers at the rate you'll actually be quoted.
The Layers The Cash-On-Cash Number Misses
Cash flow isn't the whole return.
Loan paydown. About $350 of Ryan's monthly payment goes to principal — roughly $4,200 in the first year. His tenant paid it.
Tax benefits. On properties over $400,000, Ryan runs a cost segregation study, which accelerates depreciation and produced about $18,000 in first-year tax savings on this deal.
📍 Before You Count On That $18,000
This is the least transferable number on the page, and we'd rather say so than let it inflate your expectations. Whether you can use depreciation losses this way depends on passive activity loss rules, whether you or your spouse qualify as a real estate professional, and your overall tax picture. A W-2 earner with one rental generally cannot replicate it. Talk to a CPA who works with investors before you assume any of it applies. Educational information, not tax advice.
Appreciation, which Ryan deliberately doesn't underwrite for — though he'll tell you most of his real estate returns have come from it.
Add cash flow, paydown, and tax savings and the first-year total on that Nashville property was about $28,896 on $110,000. But note what that mixes together: only the $6,696 is money you can spend. The rest is equity and tax position.
That's why cash-on-cash is the number to optimize. It's the one that's liquid.
One Warning
Property taxes get reassessed at your purchase price, not the seller's. Zillow's tax history shows what the current owner pays, which can be far below what you'll owe.
Savvy learned this the expensive way on her San Jose flip — she paid $900,000 and Santa Clara County assessed at $1.3 million, sending a $4,000 supplemental bill on top of the $2,000 she'd already paid.
Look up the local rate, multiply by your purchase price, and budget that number.
Run The Numbers Before You Make The Offer
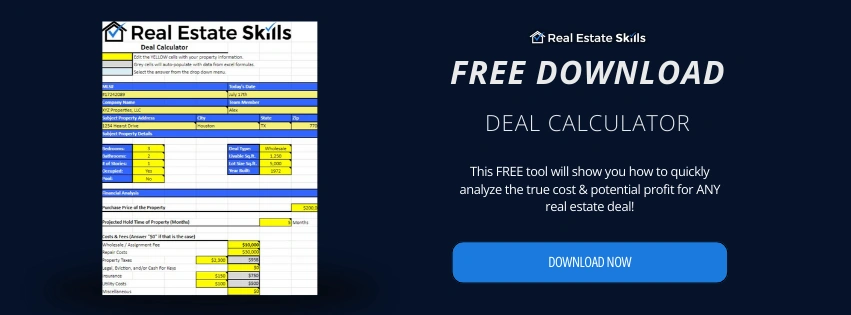
You just watched a real rental go from a 6.1% return to 2.8% on nothing but a change in interest rate. That's how thin the margin between a good deal and a bad one actually is — and it's why the math has to be right before you commit, not after. Our free Deal Calculator does it for you. Plug in the purchase price, rent, expenses, and financing terms, and it returns your cash flow, cash-on-cash return, and maximum allowable offer. It's the same spreadsheet our students use to evaluate a property before they ever submit an offer — and to walk away from the ones that don't work.
You Can Run The Numbers. Now Learn To Find Deals Worth Running Them On.
Analyzing a property is the easy half. The hard part is having enough deals crossing your desk that you can afford to say no to the ones that don't work. Our FREE Training walks through the whole system — how to source discounted properties, get them under contract, and close them — the same one thousands of our students use. Watch it today, then go run the numbers on a deal you found yourself.
Watch The FREE Training →How To Finance A Real Estate Investment
Conventional loans offer the lowest rates but need 20–25% down and 30–45 days. Hard money closes in 7–10 days and qualifies on the deal, at 10–18% interest. Private money, home equity, and DSCR loans fill the gaps between them.
Most beginners cross strategies off the list because of the down payment, not realizing how many ways there are to reduce or eliminate it.
| If This Is You | Use | Watch For |
|---|---|---|
| W-2 income, 680+ credit, buying a rental | Conventional | 20–25% down, 30–45 days to close, won't finance distressed property |
| Buying distressed, need speed | Hard money | 10–18% interest — every extra month eats your margin |
| Thin credit, self-employed, need gap funding | Private money | Terms vary widely; always paper it, even with family |
| Own a home with equity | HELOC or cash-out refi | Your residence is the collateral |
| Self-employed or maxed on conventional loans | DSCR | 20–25% down, 1–2% above conventional, often prepayment penalties |
Conventional Loans
The cheapest money available, and the slowest. Expect 20–25% down on a single-family rental, up to 30% on multi-unit. Lenders check credit, two years of income, and want reserves covering several months of expenses. You generally can't count the property's future rent to qualify.
The catch for investors: conventional lenders won't finance a property that isn't habitable. If it needs a kitchen, this isn't your loan.
Hard Money
Short-term, asset-based lending — the lender underwrites the deal, not you. Closes in 7–10 days, and the right lender funds 100% of the rehab on top of the purchase.
You pay for that speed. Rates run 10–18% plus points, terms are six to twelve months, and the clock is expensive. Savvy carried her San Jose flip for six months at 15% down and two points. Fifty of those days were lost because her agent wouldn't read the inspection report — fifty days of interest for nothing. Here's what a hard money loan actually costs.
Three things worth knowing before you sign, from Alex:
- How they charge interest on rehab draws. Some lenders charge on the full loan from day one, even on money you haven't drawn. Better ones charge only on what you've actually used. On a six-month flip, that difference is thousands.
- Whether they allow accrued interest. Some let you defer payments until sale or refinance rather than paying monthly. When cash is tight mid-rehab, that flexibility is worth a slightly higher rate.
- Whether they allow a second position lien. If they won't fund everything you need, this lets you raise the rest elsewhere — which is how the stacking below works.
Build these relationships before you're under contract. Desperate borrowers get worse terms, and the same deal submitted to three lenders comes back with meaningfully different rates, points, and leverage. Savvy found hers at an online lender meetup and could email at night for a proof-of-funds letter by morning.
One red flag: you shouldn't pay money out of pocket before closing, apart from an appraisal. Application fees charged upfront are a warning sign.
Private Money
Individuals rather than institutions — family, business contacts, other investors. Terms are whatever both parties agree to, which is the advantage and the risk. Always use a written loan agreement regardless of the relationship. More on private money lending.
Private money is what makes zero-down deals actually work. Hard money covers most of the purchase and rehab; private money covers the down payment and closing costs on top of it.
📓 From The Field
Alex's Del Marino Avenue flip ran exactly that way. He bought at $390,000, renovated for $42,000, sold for $535,000, and cleared over $60,000 in about 90 days — using a combination of hard money and private lenders for the entire purchase and rehab. None of it was his own capital. Individual results vary; leverage magnifies losses as well as gains.
Worth being clear about why that worked, because it wasn't just the financing. He'd been wholesaling first, so he already knew how to find a deal worth doing and already knew which contractors his cash buyers used and which ones actually delivered. The rehab was $42,000 and mostly cosmetic — new cabinets, flooring, fixtures, paint. Small budgets de-risk projects: fewer walls opened means fewer change orders and fewer delays.
Leverage magnifies losses as well as gains. A zero-down deal with a bad rehab estimate is a fast way to lose money that isn't yours.
Home Equity
A HELOC, home equity loan, or cash-out refinance can access up to about 80% of your equity at rates far below hard money. A HELOC gives you a revolving line at variable rates; a home equity loan is a fixed lump sum; a cash-out refi replaces your mortgage at a higher balance.
The tradeoff is unambiguous: your home is the collateral. If the deal goes wrong, that's what's at risk. And in a 6–7% environment, a cash-out refi means giving up whatever rate you're currently sitting on.
DSCR Loans
Debt Service Coverage Ratio loans qualify on the property's rental income rather than your personal income — no tax returns, no W-2. The lender divides gross rent by total debt obligations; most want 1.1 to 1.25 or better.
Genuinely useful if you're self-employed, write off significant income, or have hit the conventional loan limit. Expect 20–25% down, rates 1–2% above conventional, and frequently prepayment penalties.
A DSCR loan solves a qualification problem, not a capital problem. If you don't have the down payment, it doesn't help.
Loan terms and availability vary by lender, market, and borrower. This is educational information, not financial advice — confirm current terms directly with lenders before making decisions.
You Don't Need Your Own Money. You Need The Right Process.
Alex bought and flipped a property without using a dollar of his own capital by stacking hard money and private money. That's not a trick — it's what happens when you know how to find a deal worth funding and who to call. Our FREE Training shows you the entire system, from sourcing discounted properties to closing them with other people's money. Watch it today.
Watch The FREE Training →Where Should You Invest In Real Estate?
Buy where the numbers work, not where the headlines point. Expensive coastal metros rarely cash flow; secondary markets often do. Look one to two hours outside a major city, or start in your own backyard where you already know the streets.
Real estate is local. A deal structure producing 10% cash-on-cash in Cleveland can produce negative cash flow on the same terms in Los Angeles. National data tells you almost nothing about whether a specific property works.
Four practical approaches, each one something our team has actually done.
Look One To Two Hours Outside An Expensive City
If you're in San Francisco, Boston, San Diego, or Miami, finding a property that cash flows at today's rates is genuinely hard. Prices are too high relative to rents.
Ryan puts the gap plainly: a million-dollar home in his San Diego market would cost under $300,000 for the equivalent property in Memphis, Tennessee. That's why he invests out of state. His Nashville rental — $417,000, $3,300 rent — produces a ratio that simply doesn't exist in coastal California.
Start by looking at cities within a couple hours of where you live. You keep some local knowledge while getting meaningfully better numbers.
Or Invest In Your Own Backyard
The opposite approach, and it works for a different reason.
Our student John bought his first rental 1.8 miles from his house. He drove past the community every day on his commute, noticed new units going in, stopped, and talked to a man sitting outside — who turned out to be the community's maintenance manager. That conversation produced a phone number, which produced the deal. The community now calls him first when titles clear.
He also can be there in two minutes if something breaks, versus 45 minutes to Orlando. On a first property, being close enough to handle problems yourself is worth real money.
Hyper-local knowledge is a genuine edge. You know which streets are improving, which are struggling, and what things actually rent for — because you live there.
Follow Institutional Capital, But Check Who's Living There
When Ryan bought in Nashville, he pulled title records on neighboring properties and recognized large hedge funds among the owners. That told him something was happening in that neighborhood.
But he also noticed most of the homes were owner-occupied — which mattered more. Owner-occupants maintain properties, stay longer, and support appreciation in a way an all-rental block usually doesn't.
Both signals together are stronger than either alone. Anyone can pull ownership records on a county assessor's site.
Know The Regulatory Environment Before You Buy
📍 Check These Before You Buy In A New Market
Local rules can decide whether a deal works at all. Confirm each of these with a local property manager or real estate attorney:
- Rent control. California's Tenant Protection Act (AB 1482) caps annual increases at 5% plus local CPI, maximum 10%, on most residential properties built before 2005. Similar laws exist in New York, Oregon, and municipalities across New Jersey and Washington.
- Just-cause eviction requirements and notice periods. These vary widely and affect how quickly you can address a non-paying tenant.
- Short-term rental ordinances. Municipal rules have tightened significantly since 2022, and a change can end the business model on a property you already own.
- Who closes deals in that state. Title companies in Colorado, attorneys in Illinois, title plus escrow in California. Build that relationship before you have a deal on the clock.
Rent control, landlord-tenant, and short-term rental laws vary by state and municipality and change frequently. Confirm current requirements locally before purchasing.
What Actually Matters
Beyond the specifics, you're looking for the same handful of things in any market: job growth and employer diversity, population moving in rather than out, rent-to-price ratios that let a property cash flow at today's financing costs, and a regulatory environment you can live with.
What you're not looking for is whichever market is currently being written about. By the time a market is a headline, the easy deals are gone.
Is Real Estate A Good Investment?
Real estate offers something no other mainstream asset does: leverage. A $25,000 down payment controls a $250,000 property, so appreciation compounds on the full value while your tenant pays down the loan. It's also illiquid, management-intensive, and concentrated.
Yes — with real caveats, and for reasons more specific than "property goes up."
What Real Estate Does That Stocks Don't
The honest starting point: stocks are a legitimate wealth-building vehicle. The S&P 500 has averaged roughly 10% annually over the last century, about 7% after inflation. Alex owns index funds. Nobody here is telling you not to.
The difference comes down to one word: leverage.
Put $25,000 into an index fund at 10% a year and in 30 years you have roughly $436,000. That's a good outcome.
Put the same $25,000 down on a $250,000 rental property. At just 4% annual appreciation — below the long-run average — that property is worth about $811,000 in 30 years. And you collected rent the entire time while a tenant paid down the mortgage.
You didn't get a better return rate. You got the return on $250,000 instead of on $25,000.
💡 How Leverage Works On A Shorter Timeline
- You buy a $200,000 property with $20,000 down.
- The property appreciates to $300,000 — a 50% increase.
- Your loan balance is still around $180,000.
- Your equity is now $120,000. Your $20,000 became six times your money — while the property itself only rose 50%.
That gap is leverage, and no brokerage account offers it.
The Other Advantages
Cash flow arrives monthly whether the market is up or down. Stocks pay nothing unless you sell or collect a dividend.
Tax treatment is genuinely different. Residential rental property depreciates over 27.5 years per IRS Publication 527, producing a paper loss that can offset income even as the property gains value. Mortgage interest is deductible. A 1031 exchange defers capital gains when you roll into a like-kind property. Whether and how much of this applies to you depends on your income and filing situation — talk to a CPA.
You control the asset. You decide when to buy, what to renovate, how to price the rent, when to refinance, when to sell. Stock investors control none of those variables.
It's a reasonable inflation hedge. Rents and property values tend to rise with inflation while a fixed-rate mortgage payment stays flat.
What Can Go Wrong
Every one of these is real, and every one has a mitigation.
- Tenants. Missed rent, damage, evictions that take months. Screen properly: credit, income verification, employment, and calls to prior landlords about payment history.
- Vacancy. An empty property still costs you the mortgage, taxes, and insurance. Budget 8% — about one month a year — into every underwrite.
- Unexpected repairs. Roofs, HVAC, plumbing. Reserve 5% of gross rent on new construction, 10–20% on older properties.
- Illiquidity. You cannot sell a house in an afternoon. Savvy's Oakland flip sat 49 days with two price reductions and hadn't sold. That's an experienced investor with a good property in a slow market — it happens.
- Rate risk. As we showed earlier, 1.5 points of interest cut a real deal's cash-on-cash from 6.1% to 2.8%. Underwrite at the rate you'll actually get.
- Overleveraging. The flip side of leverage: it magnifies losses just as efficiently. Keep reserves. Don't borrow past what you could service at reduced occupancy.
- Concentration. One property in one market is not a diversified portfolio, however good the numbers look.
The Honest Comparison
Real estate isn't better than stocks on every axis. Stocks are more liquid, easier to diversify, and require no management whatsoever. If you want to deploy capital and never think about it again, index funds are the better instrument and this is the wrong article.
What real estate offers is leverage, monthly income, tax advantages, and control — four things a brokerage account structurally cannot provide. That combination is why it's built more everyday wealth than almost any other asset.
It just isn't passive, and anyone telling you otherwise is selling something.
Past performance doesn't guarantee future results. All investing carries risk, including loss of principal.
10 Tips For New Real Estate Investors
Build credit before you need it, run the numbers on every deal, and get landlord insurance — a standard homeowners policy won't cover a rental. Screen tenants on credit, income, and prior landlord references. Know your state's security deposit rules.
These aren't motivational. They're the things that cost money when you get them wrong.
1. Build Your Credit Before You Need It
A 700+ score gets you materially better loan terms, and the difference compounds over 30 years. Pay everything on time, set up autopay on recurring bills, keep utilization low, and treat a credit card like a debit card — never carry a balance. Ryan keeps his at 811 and treats it as a business asset, because that's what it is.
2. Hold Properties In An Entity
An LLC separates your real estate from your personal assets and limits your liability. You don't need one to write a contract or assign it, but for anything you're going to own, it's worth doing. It also looks more professional to sellers. Confirm the structure with an attorney in your state.
3. Run The Numbers On Every Single Deal
No exceptions, and no delegating it. The first agent Ryan worked with pitched him a rental she called excellent; he ran it himself and found he'd lose nearly $1,000 a month at her price. Be a shopper, not just a buyer.
4. Get Landlord Insurance
This one catches people. A standard homeowners policy does not cover a property you rent out. Landlord insurance — sometimes called a dwelling policy — covers the structure, liability, and often loss of rental income. If you convert a home to a rental and don't update the policy, you may be uninsured for the thing most likely to happen.
5. Screen Tenants Properly
The most expensive mistake in rentals is the wrong tenant. Run a credit check. Verify current employment. Ask about rental history, why they're moving, and how long they intend to stay. Then actually call prior landlords and ask whether they paid on time and would rent to them again. The reference call is the step people skip and the one that tells you most.
6. Know Your State's Security Deposit Law
Deposit rules are strict and they vary — how much you can collect, where it must be held, how fast you must return it, and what documentation is required for deductions. Mishandling a deposit creates real legal exposure over a small amount of money. Look up your state's rules once and follow them exactly.
7. Act Fast On Problems
Delayed repairs and unaddressed late rent almost always cost more than handling them immediately. A small leak becomes a floor. One missed payment becomes three. Address things in the week they happen.
8. Consider A Property Manager
They typically take 8–10% of gross rent and handle tenant screening, maintenance, and turnovers. Whether that's worth it depends on your time and distance. Ryan self-manages his Nashville rental from out of state — but he still budgets 8% in every underwrite, because he'll eventually delegate it and the deal has to work when he does.
9. Use The Tax Benefits Deliberately
Depreciation, mortgage interest, property taxes, insurance, management fees, and maintenance are all deductible on a rental. Residential property depreciates over 27.5 years per IRS Publication 527. On larger properties, a cost segregation study can accelerate that considerably. Get a CPA who works with real estate investors specifically — this is not general tax preparation.
Educational information, not tax advice. Tax treatment depends on your individual circumstances.
10. Know Your Exit Before You Buy
Every property should have at least two exits defined before you close. Sell, refinance and hold, 1031 into something larger, or convert the use. Markets shift faster than renovation timelines, and a backup exit isn't pessimism — it's what keeps a slow market from becoming a forced sale.
One more, and it's the one people actually need: make an offer.
Analysis paralysis is the single most common reason people never close a first deal. They consume videos for a year, build spreadsheets, and never submit anything. Brayden targets five to ten written offers a day. Most get rejected — that's the job, not a verdict.
The experience from your first deal, including everything that goes wrong in it, is worth more than another six months of preparation.
8 Mistakes That Cost New Investors Money
The expensive mistakes are predictable: giving up your margin before you've confirmed you can recover it, underestimating rehab costs, finding a property before you have a buyer, and letting a passive agent or contractor cost you months of carrying costs.
Most beginner mistakes aren't exotic. They're the same handful, and every one below actually happened to someone in this guide.
1. Giving Up Your Margin Before You've Secured It
John had a property under contract with a $10,000 assignment fee planned. His cash buyer walked it, found foundation issues, and said the number didn't work.
So John gave up the entire $10,000 — confident he could go back to his agent, renegotiate the purchase price down, and recover it on that side.
The agent wouldn't move. That was the number.
Now he'd conceded his whole fee with nothing to recover it from. He told the buyer plainly: I shot myself in the foot, I gave you my entire assignment fee, is there something we can work out. The buyer absorbed a $4,000 hit himself and let John keep $4,000.
The tactical lesson: never concede your margin until you've confirmed you can recover it somewhere else. Get the reduction in writing first, then pass along whatever you choose to.
The bigger lesson is what the buyer told him afterward — he gets calls from wholesalers every day, and John's honesty was what decided whether he'd work with him again. He now wants first look at everything John finds. A $6,000 lesson bought a buyer relationship worth considerably more.
2. Finding The Property Before You Have The Buyer
Robert lined up three vetted cash buyers before he had a property under contract. When he got one, he sent it to all three, one took it at his price, and he assigned within 72 hours — before his own earnest money was even due.
Brayden did it backwards. Found good deals first, couldn't move them, canceled contract after contract, and eventually needed a partner to cover his earnest money and split his fee.
Build the buyer list first. Always.
3. Underestimating The Rehab
Renovation budgets are almost always wrong on the low side. Get at least two itemized bids — three is better — not round-number estimates. Build in a 20–25% contingency before you make the offer.
And establish contractor relationships before you have a deal on the clock. Savvy had to fire a contractor mid-project for overcharging, which cost her time and money on a hard money loan. The most expensive contractor mistake is hiring the wrong one under pressure.
4. Letting A Passive Service Provider Cost You Months
Savvy's first buyer walked because a harshly written inspection report spooked them — even though she'd fixed everything in it. She asked her agent roughly ten times to read the report and document the repairs. He never did.
Fifty days lost. Fifty days of hard money interest. And the market shifted underneath her in the meantime, so she relisted lower and sold for less than her first offer.
She fired him on a Friday night, found a new agent Saturday morning, and closed. Her lesson: when someone is costing you money, move. Don't hold on.
How She Flipped A Distressed Property In San Jose For $65K Profit
Real Estate Skills student Savvy breaks down her most distressed fix-and-flip yet — including the contractor and the agent she fired mid-project, and what each mistake cost her.

5. Not Knowing What Your Taxes Will Actually Be
Property taxes get reassessed at your purchase price, not the seller's. Savvy paid $900,000 for her San Jose duplex and Santa Clara County assessed it at $1.3 million — a $4,000 supplemental bill on top of the $2,000 she'd already paid.
Look up your local rate and multiply by your price. Not the seller's, and not what Zillow's history shows.
6. Assuming Every Title Company Will Work With You
Robert's assignment nearly died at closing because the title rep objected to a wholesaler making money on the deal — arguing it should go to the seller. It took a five-way call between the agent, buyer, lender, and others to save it.
Find an investor-friendly title company or closing attorney before you need one, and know who handles closings in your market. It's title companies in Colorado, attorneys in Illinois, title plus escrow in California.
7. Skipping Due Diligence Because The Deal Feels Urgent
Always inspect in person. Always pull permit history with the municipality. Always verify claimed rental income against actual leases and bank statements.
A motivated seller and a tight timeline are reasons to be more rigorous, not less. The deal that closes fast because you skipped steps is rarely the deal you wanted.
8. Buying On The Optimistic Number
Savvy's underwriting was right — the profit she projected on day one is almost exactly what she made. Her forecast was wrong: she expected $1.3 million and the market moved.
Underwrite conservatively and treat anything above that as upside. Use the realistic ARV, not the one that makes the deal work.
When Real Estate Investing Is The Wrong Move
Skip real estate if you need money in the next few months, have no emergency fund, carry high-interest debt, or want a genuinely passive investment. It's illiquid, slow to produce results, and none of the entry strategies are hands-off.
We'd rather tell you now than have you lose six months and a chunk of savings finding out.
You Need Money This Month
Real estate is slow. John was three months into learning before his first deal, and it paid $4,000. Robert canceled four or five contracts before one closed. Savvy's flip took six months from purchase to closing, and she didn't see a dollar until the end.
If rent is due and there's no cushion, wholesaling isn't a solution — it's a second job with delayed and uncertain pay. Get your income stable first. Real estate will still be here.
You Don't Have An Emergency Fund
Investment capital and emergency savings are separate money. If they're the same money, one bad tenant, one vacancy that runs two months long, or one HVAC replacement puts you in a position where you're making financial decisions from pressure instead of strategy.
Build the reserve first. Then invest what's left over.
You Have High-Interest Debt
If you're carrying credit card debt at 20%+, paying it down is a guaranteed return that beats what most real estate deals produce. A rental at 8% cash-on-cash doesn't beat eliminating a 22% balance. Clear the expensive debt, then invest.
You Want Something Genuinely Passive
None of these strategies are passive to start.
Wholesaling is 20–30 hours a week of calls and offers. Flipping is project management with your money at risk. Even rentals — the closest thing to passive here — mean tenant screening, maintenance calls, and vacancies, and a property manager taking 8–10% doesn't eliminate the work, it reduces it.
Rentals become relatively passive after they're stabilized. Getting there isn't.
If you genuinely want to deploy capital and never think about it again, buy index funds or REITs. That's not a consolation prize — it's the correct instrument for that goal, and we'd rather point you to it than sell you something that doesn't fit.
You Can't Tolerate Repeated Rejection
Brayden makes five to ten written offers a day. Most are rejected. Roughly ten to fifteen written offers produce one deal.
Robert had four contracts die before one closed — including one where the buyer texted him a week from closing, while he was at the gym, to say he was out. Some agents hang up when they hear "wholesaler." One told him she'd tell everyone in the market not to accept his offers.
This is normal, and it's the actual filter. Not the math, which anyone can learn in a weekend. Whether you're still sending offers in month four after the third deal has fallen apart.
You Need Certainty
Deals fall through. Savvy's Oakland flip sat 49 days with two price reductions and hadn't sold at the time we spoke — an experienced investor, a good property, a slow market. Her San Jose flip sold for less than her first offer because 50 days of delay let the market move.
If an unpredictable outcome on a large sum would genuinely damage you, this isn't the right vehicle right now.
A Thirty-Day Test
If you're unsure, try what Robert did.
He found real estate in February, knew immediately he wanted to do it — and then waited a month before spending or quitting anything. He wanted to know whether he genuinely wanted this or whether it was just an escape from a job he hated.
Give yourself thirty days. Keep learning. Don't spend money and don't quit anything.
If the interest has faded by day thirty, you have your answer and you've saved yourself a lot of money and time. If you're still thinking about it, that tells you something the excitement of week one never could.
Real Estate Investing FAQs
Final Thoughts On How To Invest In Real Estate
Real estate investing isn't one decision. It's a sequence, and the only one that matters right now is the first one.
Everyone spent the start of this year predicting rates would fall. They rose instead, and they're sitting at the highest point of 2026. That changed which deals work. It didn't change whether deals work. In this market, John collected a $4,000 assignment fee with none of his own money and bought a rental days later. Savvy finished a distressed flip in one of the most expensive markets in the country and kept $65,000. Neither of them waited for better conditions.
What separates the people who do this from the people who read about it isn't capital or timing or a market edge. It's that they eventually submitted an offer.
Be honest about where you're standing. If you have time and no money, wholesaling is your entry — nothing else lets you earn without buying. If you have a little capital and steady income, house hacking gets you an owner-occupied loan and a live-in education in being a landlord. If you have real capital and limited time, a rental gets you cash flow, appreciation, and a tenant paying down your loan simultaneously.
And if none of those fit — if you need money this month, or you're carrying expensive debt, or you want something genuinely hands-off — the honest answer is that this isn't the right time, and index funds or REITs will serve you better. That's not a failure. Knowing which vehicle fits your situation is the entire skill.
Expect it to go badly before it goes well. Robert canceled four or five contracts before one closed. John gave away his entire assignment fee on his first deal and salvaged $4,000 through nothing but honesty. Savvy fired a contractor and an agent on the same project and still walked away with $65,000. None of that is failure — it's the shape of the work.
So here's your next move, and it costs nothing. Pick the strategy that matches your capital. Then take one action this week that fits it.
- Wholesaling: find five cash buyers in your market — Facebook investor groups, a local REIA meetup, or whoever's already buying distressed houses near you. Just five names. Robert had three vetted buyers before he ever had a property, and that's why he assigned in 72 hours without touching his own money.
- Rentals: pull up three properties currently listed in your target market and run the full numbers on each — rent, mortgage, taxes, insurance, maintenance, vacancy, management. Not to buy them. To find out whether you can tell a good deal from a bad one yet.
- House hacking: call a lender and find out what you actually qualify for at 3.5% down.
That's it. Not a course, not a mentor, not more videos. One action this week that produces information you don't currently have.
If it helps to have the frameworks in front of you while you work, our free real estate investing PDFs and templates cover the deal calculators, contracts, and checklists referenced throughout this guide.
The market will keep moving whether you act or not. The only variable you control is whether you know your numbers when the right deal shows up.
The Market Isn't Waiting. Neither Should You.
Rates rose when everyone said they'd fall, and the investors who kept moving closed deals anyway. Our FREE Training walks you through exactly how to find discounted properties, analyze them correctly at today's numbers, and close your first deal — the same system thousands of our students use. Watch it today, then go take the one action you picked above.
Watch The FREE Training →
About The Author
Founder & CEO, Real Estate Skills
Alex Martinez is the Founder and CEO of Real Estate Skills. He has wholesaled and flipped houses for over 14 years, been part of 1,000+ real estate transactions, and personally acquired 33+ residential investment properties. Through Real Estate Skills, Alex and his team have trained more than 6,000 investors nationwide on how to find deals, analyze them correctly, and close them.
Real Estate Skills is not a law firm, tax advisor, or registered investment advisor, and the information in this article is provided for educational purposes only — it does not constitute legal, tax, or financial advice. Real estate laws, lending terms, and tax treatment vary by state and change over time. All investing carries risk, including loss of principal, and the individual results described in this article are not typical or guaranteed. Always consult a licensed real estate attorney, CPA, and your own financial advisors before entering into any contract or transaction.
👉FREE Training
How To Consistently Wholesale, Flip Houses, & Invest In Rental Properties From The MLS
(Without Spending $1 On Marketing)

Alex Martinez, the founder of Real Estate Skills, is known for his strong, practical expertise in real estate, starting from a beginner with no family connections in the industry to acquiring over 55 real estate deals, including wholesale and flips, within his first year.
He has dedicated his career to providing cutting-edge education and resources for real estate professionals. He emphasizes the importance of self-taught knowledge through mentors, books, and hands-on experience.
His journey from earning a modest income to becoming a successful real estate entrepreneur and educator showcases his expertise and dedication to the field.

Ryan Zomorodi, co-founder and COO of Real Estate Skills, leverages his experience from a diverse background in real estate investment, construction management, and entrepreneurship to provide comprehensive education in the real estate sector.
His expertise is rooted in hands-on experience, extensive industry knowledge, and a commitment to empowering others through education.
Ryan's journey reflects a blend of practical experience and entrepreneurial success, contributing to his role in developing a platform that educates and supports aspiring real estate professionals.
Read Ryan's Full Bio >>
