Bonus Depreciation: 2026 Rules for Real Estate Investors
Oct 28, 2026
Written by
Alex Martinez, Founder & CEO, Real Estate Skills. Has wholesaled and flipped houses for over 14 years, been part of 1,000+ real estate transactions, and personally acquired 55+ residential investment properties. Has trained 6,000+ investors nationwide.
Reviewed by
Ryan Zomorodi, Co-Founder & COO, Real Estate Skills. Reviewed the tax rules, examples and IRS sources in this guide before publication.
Publication history: Originally published November 10, 2025. Updated October 2026 to reflect the permanent 100% bonus depreciation rate under the One Big Beautiful Bill Act and IRS Notice 2026-11, with corrected rate history, 2026 Section 179 limits, recapture rules, new real estate worked examples, and new sections on W-2 income limits and the downsides of bonus depreciation. Tax rules, examples and IRS sources reviewed by Ryan Zomorodi, Co-Founder & COO of Real Estate Skills.
Bonus depreciation lets you deduct the full cost of qualifying property in the year it's ready to use, instead of over many years. For property acquired after January 19, 2025, the rate is a permanent 100%. In real estate, it covers a building's short-life parts, never the land or structure.
You've probably heard some version of the pitch. Buy a rental, run a cost segregation study, write off six figures in year one. Part of that is true. Bonus depreciation came back at 100% in 2025, and this time Congress made it permanent. But the people selling the pitch usually skip the two details that decide whether it saves you a dime.
I've personally acquired more than 55 residential investment properties, and I'll tell you what I tell my students. You don't get to write off the purchase price. You write off the parts of the property that wear out fast: the flooring, the appliances, the driveway. And the deduction only cuts your taxes if you're allowed to use the loss this year. Miss either point and you end up with an impressive number on paper, no real savings, and a tax bill waiting for you at the sale. That bill has a name, depreciation recapture: the IRS taxing back the depreciation you claimed.
This guide covers the current rules and how the rate changed, what qualifies, two worked examples with real numbers, who can actually use the deduction, and when skipping it is the smarter move. It's written for investors, not accountants, so every term gets explained the first time it shows up. Before you run the tax math on any property, make sure the deal works on its own. Download our free Rental Property Calculator and check the cash flow first.
Educational only, not tax advice. Bonus depreciation rules interact with your income, entity and state, so run your numbers with a CPA before you file.
What Is Bonus Depreciation?
Bonus depreciation is a federal tax deduction, under Section 168(k), that lets you write off the cost of qualifying property in the first year instead of over its normal 5-to-20-year schedule. The IRS calls it the special depreciation allowance. It changes when you deduct the cost, not how much.
Start with plain depreciation. When you buy something for a rental or a business that wears out over time, the IRS won't let you deduct the full cost the year you buy it. You deduct a slice each year over its recovery period, which is the number of years the IRS assigns to that type of property.
The schedule is called MACRS (the Modified Accelerated Cost Recovery System), and the IRS lays it out in IRS Publication 946. Appliances and carpet in a rental get 5 years. Driveways, fencing and landscaping get 15. A residential rental building gets 27.5, and a commercial building gets 39. Bonus depreciation is the most aggressive form of accelerated depreciation, and it lets you skip the wait on anything with a recovery period of 20 years or less. You deduct the full cost in the year the property is placed in service, meaning it's ready and available for its intended use. A rental appliance counts once it's installed and the unit is available to rent, even if no tenant has moved in yet.
Here's what that looks like. Say you put $10,000 of new appliances and carpet into a rental in 2026:
- Regular depreciation: about $2,000 in year one (5-year schedule, half-year convention), with the rest spread over the following five tax years.
- Bonus depreciation: the full $10,000 in year one.
- What it's worth: in a 24% tax bracket, that's roughly $2,400 off this year's tax bill instead of about $480, assuming you're allowed to use the deduction this year. That's its own question, and I cover it below.
The part most beginners miss: bonus depreciation doesn't create a new deduction. Over the life of that carpet and those appliances, you deduct the same $10,000 either way. You're pulling future deductions into today. That's worth a lot, because tax you save now can fund your next deal. It also means less depreciation in later years and a bigger taxable gain when you sell.
It's automatic, too. If the property qualifies, bonus depreciation applies unless you opt out, and per the IRS bonus depreciation FAQ, opting out is done class by class (all your 5-year property for that year, for example) with a statement attached to Form 4562, the IRS depreciation form, by your filing deadline.
What Is The Bonus Depreciation Rate In 2026?
The bonus depreciation rate in 2026 is 100% for property acquired and placed in service after January 19, 2025, with no phase-down. Property acquired under a binding contract signed before January 20, 2025 stays on the old schedule: 40% if placed in service in 2025, 20% in 2026.
Most of what you'll read online about the rate is out of date. For years the rule was a phase-down: 100% through 2022, then 20 points lower every year until it hit zero in 2027. Plenty of articles still show that schedule.
It changed on July 4, 2025, when the One Big Beautiful Bill Act made 100% bonus depreciation permanent for property acquired after January 19, 2025. The IRS issued interim guidance on the new rules in January 2026 in IRS Notice 2026-11.
| When the property was acquired and placed in service | Bonus depreciation rate |
|---|---|
| Placed in service 2015 through 2017 (acquired before September 28, 2017; new property only) | 50% |
| Acquired before September 28, 2017, placed in service in 2018 | 40% |
| Acquired before September 28, 2017, placed in service in 2019 | 30% |
| Acquired after September 27, 2017, placed in service through 2022 | 100% |
| Placed in service in 2023 | 80% |
| Placed in service in 2024 | 60% |
| Acquired before January 20, 2025, placed in service in 2025 | 40% |
| Acquired before January 20, 2025, placed in service in 2026 | 20% |
| Acquired before January 20, 2025, placed in service in 2027 or later | 0% |
| Acquired and placed in service after January 19, 2025 | 100%, no expiration date |
Certain long-production property and aircraft get an extra year on some rows. Used property only qualifies for bonus depreciation if it was acquired after September 27, 2017.
What "Acquired" Means (The Trap For Real Estate Investors)
The date that decides your rate is when you acquired the property. For anything you buy, the IRS generally treats that as the date you signed a written binding contract, not the closing date. That catches investors more than anyone, because purchase agreements are often signed weeks or months before closing. If you closed a deal in early 2025, this is the first thing I'd check.
💡 Example: Contract Date vs. Closing Date (Hypothetical Numbers)
- You sign a purchase agreement on a single-family rental on December 12, 2024.
- It closes February 20, 2025, and you list it for rent in March 2025.
- A cost segregation study separates out $40,000 of 5- and 15-year components.
- Because the contract was signed before January 20, 2025, those components get 40% bonus depreciation: $16,000, not $40,000. The remaining $24,000 is depreciated on the regular schedule.
- If a renovation pushes the rent-ready date into 2026, the rate drops to 20%: $8,000.
- Same house, contract signed January 22, 2025 instead: 100%, the full $40,000.
Two details matter here, and both are worth raising with your CPA:
- New purchases are separate acquisitions. A replacement furnace or new appliances you buy for that house after January 19, 2025 are acquired on their own date and can qualify for 100%, even when the house itself doesn't.
- Not every signed contract counts as "binding" for this rule. Under the IRS regulations, a contract that caps the buyer's damages at less than 5% of the price may not be treated as binding. A purchase agreement where your only risk is a small earnest money deposit can fall into that gray area, which could change your acquisition date. Don't assume either way. Have your CPA read the contract.
Can The Rate Change Again?
Yes. "Permanent" means today's law has no expiration date, not that Congress can't rewrite it. As of 2026, the rate is 100% for qualifying property, and that's the number to plan around until the law says otherwise.
Educational only, not tax advice. Acquisition dates, contract terms and placed-in-service dates all affect your rate, so confirm with a CPA before you file.
What Qualifies For Bonus Depreciation?
Property qualifies for bonus depreciation if it has a recovery period of 20 years or less, is used in a business or rental, and meets the new-or-used acquisition rules. For investors, that means appliances, carpet, furniture and land improvements like driveways and fencing. Land and buildings never qualify.
The test comes down to recovery period. If the IRS gives something a depreciation schedule of 20 years or less, it's in. If it's 27.5 or 39 years, it's out. The IRS lists the rental-specific periods in IRS Publication 527.
What typically qualifies on a rental:
- 5-year property: appliances, carpet, and furniture you provide to tenants.
- 7-year property: office furniture and equipment you use to run the rentals.
- 15-year land improvements: driveways, sidewalks, fences, parking areas, and landscaping tied to the building. General clearing and grading count as part of the land, and land is never depreciable.
- Qualified improvement property (QIP), commercial buildings only: interior improvements made after the building was first placed in service. Enlargements, elevators and escalators, and the internal structural framework are excluded. QIP doesn't apply to residential rentals at all.
- Off-the-shelf software you use in the business.
What never qualifies:
- Land. It doesn't wear out, so it's never depreciable.
- The building itself: 27.5 years for residential and 39 for commercial. On a residential rental, that also includes structural parts like the furnace, the plumbing and the roof. A new roof on your duplex is 27.5-year property, not bonus property.
- Property you're flipping. A house held for resale is inventory, and inventory can't be depreciated at all. Bonus depreciation is a buy-and-hold tool, not a flipping tool. If you flip, here's how taxes on flipping houses work instead.
- Used property with the wrong history: property you or a related party used before, property you inherited, or property whose basis carries over from the seller.
- Property the IRS makes you depreciate under its slower alternative schedule (ADS). This includes listed property, like a vehicle, used 50% or less for business, and some real estate businesses that elected out of the interest-deduction limit. If you've made that election, ask your CPA before assuming anything qualifies.
The trap beginners fall into is assuming "100%" means the purchase price. It means 100% of the qualifying pieces, and on most rentals that's a minority of what you paid. The next section shows how big that slice can be.
How Bonus Depreciation Works For Real Estate
Bonus depreciation works for real estate through cost segregation: a study that splits a building's cost into 5-, 7-, 15- and 27.5- or 39-year pieces. The short-life pieces get 100% bonus depreciation in year one. The land gets nothing, and the structure depreciates on its normal schedule.
When you buy a rental, the default is simple and slow. You separate the land from the building, then depreciate the whole building over 27.5 years (residential) or 39 years (commercial). Everything inside it, from the cabinets to the carpet to the driveway, gets lumped in at the slowest rate.
A cost segregation study fixes that. It's an engineering-based report that goes through the property and assigns each component its proper recovery period. The appliances, flooring, cabinetry, site lighting and paving that were hiding inside the 27.5-year number get pulled out into 5- and 15-year buckets, and those buckets are what bonus depreciation can write off in year one. If you want to see the standard a study is held to, the IRS spells out what it expects in a quality cost segregation study. Studies cost money, and on smaller properties the fee can eat a big share of the benefit, so get the numbers run first. We break down how a study works, what it costs and when it pays off in our guide to a cost segregation study.
One detail worth knowing: you don't have to order the study the year you buy. If you've owned a rental for a few years and never broke out the components, your CPA can usually catch up the missed depreciation in the current year through an accounting-method change (Form 3115). The bonus rate still follows the original acquisition date, though. A rental bought in 2023 catches up at 2023's 80%, not today's 100%.
💡 Example 1: A Single-Family Rental (Hypothetical Numbers)
- You buy a single-family rental for $400,000 under a contract signed in 2026, and it's ready to rent in January 2026.
- You separate the land. Using the county's land-to-building ratio, $80,000 is land and $320,000 is building.
- Without a cost seg study, the whole $320,000 depreciates over 27.5 years. Year-one depreciation (January start, mid-month convention): $11,152.
- With a cost seg study, suppose it finds $38,000 of 5-year property (appliances, carpet, cabinetry) and $26,000 of 15-year land improvements (driveway, fencing, landscaping). That's $64,000, or 20% of the building.
- That $64,000 takes 100% bonus depreciation: $64,000 in year one.
- The remaining $256,000 depreciates over 27.5 years: $8,922 in year one.
- Year-one total: $72,922, versus $11,152 without the study.
💡 Example 2: An 8-Unit Apartment Building (Hypothetical Numbers)
- You buy an 8-unit building for $1,200,000, and it's ready to rent in July 2026.
- $240,000 is land and $960,000 is building.
- Without a cost seg study, year-one depreciation for a July start is $16,003. Starting mid-year cuts the first-year building deduction roughly in half.
- With a cost seg study, suppose it finds $115,000 of 5-year property and $85,000 of 15-year land improvements (parking lot, site lighting, landscaping), for $200,000 in total.
- That $200,000 takes 100% bonus depreciation: $200,000, regardless of what month you start renting.
- The remaining $760,000 depreciates over 27.5 years: $12,669 in year one.
- Year-one total: $212,669, versus $16,003 without the study.
The component splits above are illustrations, not benchmarks. Real studies vary widely with property type, age, finishes and site work, so a quote from a cost segregation firm is the only number worth planning around. Results vary.
Two things to keep in mind before you get excited about those totals:
- A deduction only saves money if you can use it. In Example 1, if you could use the full deduction against income taxed at 24%, the extra $61,770 in year one would be worth about $14,800 in tax. For most investors with a full-time job, though, that loss is passive, and it can't touch their W-2 income. The next section covers who can actually use it.
- The IRS takes some of it back when you sell. The faster you depreciate, the more recapture you face at sale. We come back to the 8-unit building in the recapture section to run that math.
My rule on this is simple: a tax break never rescues a bad deal. Make sure the property works without it.
Run The Cash Flow Before You Count The Tax Break
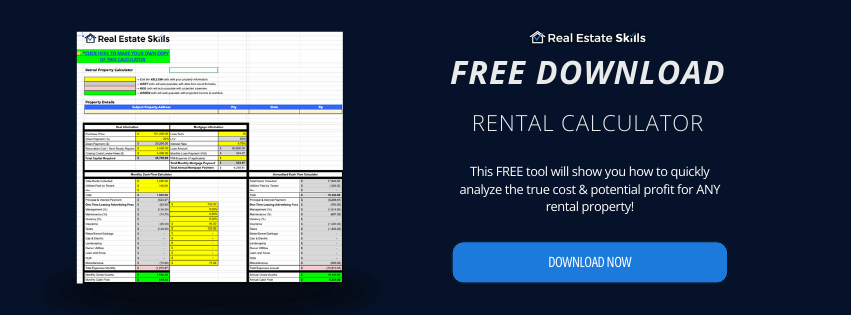
Bonus depreciation can make a rental look better on paper than it performs in real life, and a deduction is only worth something on a deal that already works. Download our free Rental Property Calculator, a spreadsheet that turns your rent and expense numbers into the property's cash flow, cap rate and return on investment, so you know the deal stands on its own before you pay for a cost segregation study.
Educational only, not tax advice. Land allocation, component classification and placed-in-service dates should come from your CPA and a qualified cost segregation provider.
Can Bonus Depreciation Offset Your W-2 Income?
Usually not. For most investors, rental losses, including bonus depreciation, are passive and only offset passive income. The exceptions are a loss allowance of up to $25,000 if your income is under $150,000, real estate professional status, and short-term rentals averaging seven-day stays that you materially participate in.
This is the part the "write off your W-2 with real estate" posts leave out. Under the IRS passive activity rules, the tax code treats rental real estate as a passive activity by default: something you invest in rather than work in. That's true even if you manage the property yourself and spend every weekend there. Passive losses can only offset passive income, such as profit from your other rentals or from a business you invest in but don't run.
So for a typical investor with a full-time job, a big bonus depreciation loss doesn't reduce the tax on their salary. What it does is still worth a lot:
- It shelters your rental income. The loss wipes out the taxable profit from that property and from your other rentals, often for years.
- Unused losses don't disappear. They're suspended and carried forward with no expiration date, and they're used up as your rental income grows.
- Selling unlocks the rest. When you sell the property in a fully taxable sale, any remaining suspended losses from it can offset your other income that year.
Three paths let rental losses reach your paycheck.
Path 1: The $25,000 Allowance (Moderate Incomes)
If you actively participate in your rental, meaning you make the management decisions like approving tenants, setting rent and signing off on repairs, you can deduct up to $25,000 of rental loss against your other income. The catch is income. The allowance starts shrinking once your modified adjusted gross income passes $100,000 and is gone at $150,000:
- $100,000 or less: up to $25,000
- $125,000: up to $12,500
- $150,000 or more: $0
Path 2: Real Estate Professional Status
If real estate is your main job, your rental losses can stop being passive. To qualify, you need to spend more than 750 hours a year in real estate trades or businesses (development, construction, brokerage, management, leasing and similar work), those hours have to make up more than half of all the hours you work that year, and you need to materially participate in your rentals. On a joint return, one spouse has to pass the hours tests alone. You can't add your hours together.
Here's the reality for most of my students: if you work a full-time W-2 job (about 2,000 hours a year), you'd need more than 2,000 hours in real estate on top of it. That's why this path usually works through a spouse who's in real estate full-time, not through the person with the day job.
Path 3: The Short-Term Rental Exception
If your property's average guest stay is seven days or less for the year (total rented days divided by the number of separate stays), the IRS doesn't treat it as a "rental activity" for these rules at all. If you also materially participate, the losses are non-passive and can offset W-2 income without real estate professional status.
The most common way investors meet material participation is spending more than 100 hours on the property during the year, and more time than any other individual, including your cleaner, your co-host and your property manager. Spending 500 or more hours also qualifies.
This is the strategy behind most of the "Airbnb wiped out my taxes" posts. It works, but it's demanding:
- The test is applied every year. One year of longer average stays can break it.
- The burden of proof is on you. You need a log of your hours kept as you go, not reconstructed in April. Hours claims are an area where taxpayers regularly lose in audits and in Tax Court when the records are thin.
- The rental has to be legal where it is. If the city shuts it down, the business case collapses, and recapture can follow.
The Ceiling Even When You Qualify
Qualifying through Path 2 or Path 3 doesn't mean the loss is unlimited. A separate rule, the excess business loss limit, caps how much net business loss can offset nonbusiness income like wages in a single year. For 2026 the limit is $256,000 for single filers and $512,000 for joint filers, and anything above it carries forward to later years as a net operating loss. This limit actually fell from 2025, when it was $313,000 and $626,000.
| Your situation | What bonus depreciation does this year |
|---|---|
| Full-time job, long-term rental, income over $150,000 | Offsets your rental income. The rest carries forward until you have passive income or sell. |
| Long-term rental, income under $150,000, you manage it | Up to $25,000 against your other income (less as income rises). The rest carries forward. |
| You or your spouse qualify as a real estate professional | Can offset W-2 and other income, up to the excess business loss limit. |
| Short-term rental averaging 7 days or less, and you materially participate | Can offset W-2 and other income, up to the excess business loss limit. |
Back to Example 1. Say you earn $180,000 at your job, and the single-family rental nets $10,000 before depreciation. The $72,922 of year-one depreciation wipes out that $10,000, leaving a $62,922 passive loss. At $180,000 of income, none of it reaches your salary, so it all carries forward. That's not wasted. It can shelter years of rental profit from this property and your others, and whatever's left gets released when you sell. What it isn't is a refund check this April. Know which row you're in before you pay for a cost segregation study.
Educational only, not tax advice. Passive activity, material participation and excess business loss rules are fact-specific and frequently audited, so work through them with a CPA before relying on a loss.
How To Claim Bonus Depreciation
To claim bonus depreciation, confirm the property was acquired and placed in service after January 19, 2025, separate land from building, identify the 5-, 7- and 15-year components, check whether you can use the loss, then report it on Form 4562. It applies automatically unless you elect out.
You don't apply for bonus depreciation. If property qualifies, it's applied automatically. Your job is to make sure it qualifies, document it, and decide whether you actually want it this year. Here's the order I'd work through it with your CPA.
Step 1: Confirm Your Two Dates
Find the date you signed the purchase contract, not the closing date. Then find the date the property was ready and available for rent, meaning listed or advertised, not the date the first tenant moved in. A contract signed after January 19, 2025, and a rent-ready date after that, means 100%. Keep the signed contract, the closing statement, and a screenshot of the first listing.
Step 2: Separate The Land From The Building
Land never depreciates, so the first number you need is how much of the price is building. Start with the purchase price plus the closing costs that get added to basis: legal and recording fees, owner's title insurance, survey costs. Then split land from building using an appraisal or the county assessor's land-to-improvement ratio.
Step 3: Identify The Short-Life Components
For a purchase, this is the cost segregation study's job. For things you buy after you own the property, the rules are simpler. If you renovate after you buy, the way investors do with the BRRRR method, every new appliance, floor and fence is its own asset with its own date, so keep every invoice. Repairs aren't depreciated at all; they're deducted as expenses in the year you pay for them. And under the de minimis safe harbor election, small items up to $2,500 per invoice or item can usually be expensed outright.
Step 4: Check Whether You Can Use The Loss This Year
Before you count the savings, place yourself in the table from the W-2 section: passive investor, the $25,000 allowance, real estate professional, or short-term rental. If the loss will just carry forward, bonus depreciation is still useful. It's just not urgent.
Step 5: Decide Whether To Take It Or Elect Out
Bonus depreciation applies unless you elect out. The election covers an entire class of property for the year (all your 5-year property, or all your 15-year property), not individual items. You make it with a statement attached to Form 4562 by your filing deadline, including extensions. It's hard to undo, because revoking it generally requires a ruling from the IRS. Investors elect out in low-income years, in states that won't follow the federal deduction, or when they plan to sell soon and don't want to front-load the recapture.
Step 6: Report It On Form 4562 And Keep The File
Bonus depreciation on rental property goes in Part II of Form 4562 (the special depreciation allowance), and the result flows to your Schedule E. Each rental business or activity gets its own Form 4562. Keep the cost segregation report, invoices, contract and closing statement for as long as you own the property, plus the years the IRS can still review the return for the year you sell. Your depreciation history is part of your gain calculation at sale.
Step 7: Check Your State
Many states don't follow federal bonus depreciation. California has long refused it, and New York, New Jersey, North Carolina and New Hampshire decoupled from the 2025 law's 100% rule, along with several others including Colorado, Illinois, Michigan, Pennsylvania and Delaware. In those states, you add the bonus deduction back to income on your state return and depreciate on the regular schedule for state purposes, which means two depreciation schedules for the same property. Conformity changes often and can differ between individual and business returns; the Council On State Taxation tracks it in a state-by-state conformity chart. Confirm your state's current rule each year.
Educational only, not tax advice. Elections on Form 4562 are difficult to reverse, so have a CPA prepare or review the return in the first year you claim bonus depreciation.
The Tax Break Starts With The Right Rental. Learn To Find It.
Bonus depreciation only pays off on a property you bought right. The investors who get the most from it start with deals bought at a real discount, then let the tax benefits stack on top. Our FREE Training walks you through how to consistently find those discounted deals and turn them into wholesale fees, flips or long-term rentals, the same system thousands of our students use. Watch it today, then go find the deal worth depreciating.
Watch The FREE Training →Bonus Depreciation vs. Section 179
Bonus depreciation is automatic, has no dollar cap, and can create a loss. Section 179 is an election capped at $2,560,000 for 2026, limited to your business income, and requires a trade or business. For most rental investors bonus depreciation does the heavy lifting. Section 179 mainly helps commercial owners.
Both let you write off qualifying property in year one instead of over years. They're built for different people, and for real estate the gaps between them matter more than the headline numbers.
| Bonus depreciation | Section 179 | |
|---|---|---|
| How you get it | Automatic unless you elect out (by class) | You elect it, asset by asset, on Form 4562 Part I |
| 2026 dollar limit | None | $2,560,000, reduced dollar-for-dollar once purchases pass $4,090,000 |
| Income limit | None. It can create a loss | Can't exceed your business taxable income. The excess carries forward |
| Rental owners | Works for any rental, including passive landlords | Requires a trade or business. Many landlords who just own rentals don't qualify |
| Driveways, fencing, parking lots | Yes (15-year property) | No. Land improvements are excluded |
| Roofs, HVAC, fire and security systems | No on any building (they're 27.5- or 39-year property) | Yes, but only on commercial (nonresidential) buildings |
| Interior improvements to commercial space (QIP) | Yes | Yes |
| Business-use requirement | Regular business or investment use | More than 50% business use |
| State treatment | Many states don't follow it | More widely followed, but some states cap it far lower |
When Bonus Depreciation Is The Better Tool
For a typical rental investor, it's not close. Bonus depreciation has no cap and no income limit, covers the 15-year land improvements Section 179 excludes, and doesn't require you to be running a trade or business. That last point disqualifies a lot of buy-and-hold landlords from Section 179 entirely. If you own a few long-term rentals and collect rent, your CPA may well conclude you aren't in a trade or business for Section 179 purposes. Bonus depreciation doesn't ask.
When Section 179 Wins
Section 179 earns its place in two situations.
The first is commercial property with a big building system to replace. Say you put a $180,000 roof on an office building you own in 2026. Bonus depreciation can't touch it, because a roof is part of a 39-year building. Section 179 can expense the full $180,000 in year one if you elect it and have at least that much business income. Without it, the roof depreciates over 39 years. Put the same roof on a residential duplex and it gets neither, because it's 27.5-year property with no shortcut.
The second is control. Bonus depreciation is all-or-nothing by class: elect out and you lose it on every asset in that class for the year. Section 179 lets you pick specific assets and dollar amounts, which helps when you want just enough deduction to bring this year's income down without creating a loss.
Using Both
The two can stack. Section 179 is applied first to the assets you choose, and bonus depreciation then covers the rest of the qualifying property. For a commercial owner, that might mean Section 179 on a new HVAC system and bonus depreciation on the parking lot and tenant-space improvements a cost segregation study identifies.
Educational only, not tax advice. Whether your rental activity counts as a trade or business for Section 179 depends on your facts, so confirm it with a CPA before electing.
Bonus Depreciation Recapture: What Happens When You Sell
Bonus depreciation recapture is the tax you pay on accelerated deductions when you sell. Depreciation on 5- and 7-year components is taxed at ordinary income rates, up to 37%. Regular building depreciation is taxed at up to 25%. A 1031 exchange can defer it, and under current law heirs' stepped-up basis erases it.
Depreciation isn't a gift. It's a loan from the IRS that you repay when you sell. Every dollar you depreciate lowers your basis (your tax cost in the property), and a lower basis means a bigger taxable gain at sale. Recapture is the IRS taxing that portion of the gain at higher rates than normal long-term capital gains.
You'll see plenty of guides say recapture tops out at 25%. That's only true for the building's regular depreciation. Here's the real breakdown:
| What you depreciated | How it's taxed when you sell |
|---|---|
| 5- and 7-year components (appliances, carpet, cabinetry, furniture) | All of it at your ordinary income rate, up to 37% |
| 15-year land improvements (paving, fencing, landscaping) | The part above normal straight-line depreciation at ordinary rates; the rest at up to 25% |
| The building's regular depreciation (27.5 or 39 years) | Up to 25% |
| Everything else (real appreciation) | Long-term capital gains rates of 0%, 15% or 20% |
On top of those rates, the 3.8% net investment income tax can apply to the gain if your income is high enough.
💡 Example: Selling The 8-Unit Building (Hypothetical Numbers)
Back to Example 2: bought for $1,200,000 and ready to rent in July 2026, with $200,000 of components taken as bonus depreciation. You sell in July 2031 for $1,500,000. For simplicity, ignore selling costs.
- Depreciation taken over five years: $200,000 bonus plus about $138,000 on the building, about $338,000 in total.
- Adjusted basis: $1,200,000 minus $338,000 is about $862,000.
- Taxable gain: $1,500,000 minus $862,000 is about $638,000.
- How that gain splits: about $171,700 at ordinary rates (all $115,000 of the 5-year components plus the roughly $56,700 of the land improvements taken above straight-line), about $166,500 at up to 25% (the building's depreciation plus the straight-line share of the land improvements), and $300,000 at long-term capital gains rates (the actual appreciation).
Compare that with no cost segregation study. You'd have taken about $175,000 of building depreciation over the same five years, all of it taxed at up to 25% at sale, and nothing at ordinary rates. The study let you deduct about $164,000 more in the first five years, and the price is that about $171,700 of your gain lands in the ordinary-rate bucket.
Whether that trade was worth it depends on two things. First, the tax rate when you deducted versus the rate when you pay it back: deduct at 37% and repay at 37%, and you've had interest-free use of that money for five years, but deduct at 24% and repay at 37%, and the timing benefit shrinks or disappears. Second, whether you could use the deduction at all. If it sat as a suspended passive loss until the sale, it gets released that year and offsets the gain, which is useful but a much smaller win than tax saved in year one and reinvested.
One more detail worth raising with your CPA before you sell: recapture on each component can't exceed the gain on that component. Five-year-old carpet and appliances usually aren't worth much at sale, so a reasonable, documented allocation of the sale price can make the ordinary-rate bucket smaller than this worst-case example.
Ways Investors Manage Recapture
Recapture can be deferred, sidestepped by not selling, or erased at death, but an installment sale won't spread it out.
- 1031 exchange. Roll the proceeds into another investment property and the gain, including recapture, is deferred. Watch the components, though. Under the IRS like-kind exchange rules, only real property qualifies since 2018, so recapture on 5- and 7-year personal property can still be triggered unless the replacement property carries enough similar property. The clock is tight, too. Per the IRS Form 8824 instructions, you have 45 days after the sale to identify the replacement property and 180 days to receive it (or less, if your tax return is due first). The sale money normally sits with a qualified intermediary, an independent company that can't be your agent or a relative, because taking control of the cash yourself can make the gain taxable. Plan this with your CPA and exchange accommodator before you list.
- Refinance instead of selling. A cash-out refinance lets you pull equity out without selling, and borrowed money isn't taxable income, so no recapture is triggered. The deferred tax is still sitting there. You've just chosen not to set it off yet.
- Hold for life. Under current law, heirs receive the property at a stepped-up basis (its value at your death), and the built-up recapture disappears.
- Don't count on an installment sale. Seller financing can spread out the capital gain, but depreciation recapture is generally taxed in full in the year of sale, even if you collect the money over years.
- Skip bonus depreciation on short holds. If you expect to sell within a few years, electing out (Step 5 above) may save you a recapture bill bigger than the deduction was worth.
Educational only, not tax advice. Recapture depends on how the sale price is allocated among land, building and components, and on your tax brackets in both the deduction and the sale years, so model the sale with a CPA before you list.
What Is The Downside Of Bonus Depreciation?
The biggest downsides of bonus depreciation: it moves deductions earlier rather than creating new ones, recapture at sale can be taxed at ordinary rates, most investors can't use the loss against their paycheck, and many states don't follow it. On short holds or low-income years, it can backfire.
Most pages present bonus depreciation as free money. It isn't, and I'd rather you hear the downsides from me now than from your CPA at the closing table when you sell.
It's a timing tool, not a tax cut. You deduct the same total cost either way. Taking it all in year one means smaller depreciation deductions in every later year, so the rental income you'd normally shelter with depreciation down the road becomes taxable sooner.
You may repay it at a higher rate. Bonus depreciation on 5- and 7-year components comes back as ordinary income when you sell, at rates up to 37%. If you deducted it in a 22% or 24% year and sell in a 35% year, you've paid more tax, not less. Regular building depreciation, by comparison, is capped at 25% on the way back.
The loss may just sit there. For an investor with a full-time job and income over $150,000, a bonus-driven rental loss is passive. It can't touch W-2 income. It carries forward until you have passive income or sell. That's not wasted, but the "save $20,000 this April" math rarely applies.
Even qualified investors hit a ceiling. Real estate professionals and short-term rental owners who can use the loss are still capped by the excess business loss limit, $256,000 single or $512,000 joint for 2026, with anything above it carried forward.
Your state may ignore it. California, New York, New Jersey and several other states don't allow federal bonus depreciation. You add it back on the state return and keep a second depreciation schedule.
The study costs money, and the paperwork is real. A cost segregation study is a professional fee paid up front, and on a smaller property it can eat much of the benefit. If you're claiming real estate professional or short-term rental status to use the loss, you need hour logs kept as you go, and those claims are a frequent audit target.
Some choices are hard to undo. Electing out applies to a whole class of property for the year, and reversing the election generally takes an IRS ruling. Decide before you file, not after.
When Bonus Depreciation Is The Wrong Move
Skip it, or elect out, if any of these describe you:
- You plan to sell within a few years. You get the deduction briefly, then hand much of it back at ordinary rates.
- This year's income is unusually low and you expect higher brackets later. Deductions are worth more in high-income years.
- The property is a flip. Property held for resale is inventory and can't be depreciated at all.
- The property is small and the loss would only carry forward. If the study fee is large relative to a deduction you can't use for years, the math may not work yet.
- Your state taxes you heavily and decouples, and you'd rather avoid running two schedules for a modest federal benefit.
When It's Clearly Worth It
Bonus depreciation pays off most for investors who hold for many years on a property that already pencils out (here's how to calculate ROI on a rental property if you haven't run those numbers), who can use the loss through real estate professional status, a qualifying short-term rental, or enough passive income from other rentals, who are in a high bracket now, and who plan to 1031 exchange or hold long-term rather than sell outright. If that's you, it's one of the most valuable tools in the tax code. If it isn't, ordinary depreciation is fine. Not every deal needs a cost segregation study.
Educational only, not tax advice. Whether bonus depreciation helps or hurts depends on your hold period, brackets, state and ability to use losses, so run both scenarios with a CPA.
Bonus Depreciation FAQs
Final Thoughts On Bonus Depreciation
Bonus depreciation is back at 100%, and this time it's permanent. It's one of the biggest tax benefits of real estate investing, but only for investors who understand what it is: a way to take tomorrow's deductions today, on the parts of a property that wear out fast.
The investors I've seen get the most from it aren't the ones chasing the biggest year-one number. They're the ones who know before they buy whether they can use the loss, how long they'll hold, and what the recapture looks like at the end. For them, a cost segregation study on the right property is one of the best moves in the tax code. For everyone else, standard depreciation still works, and that's fine.
Your next step: before you order a study on your next purchase, write down the date you signed the contract, which W-2 table row you fall in, how many years you plan to hold, and your state's bonus depreciation rule. Take those four answers and a cost segregation quote to your CPA and have them model the deal both ways. If the numbers work, take the deduction. If they don't, you just avoided a recapture bill.
Educational only, not tax advice.
Depreciation Rewards Owners. Start With Your First Deal.
Every deduction in this guide needs one thing first: a property you own, bought at the right price. Our FREE Training shows you how to consistently find discounted deals and turn them into wholesale fees, flips or rentals you hold for the long run, using the same system thousands of our students use. Watch it today, then go put what you learned here to work on a property of your own.
Watch The FREE Training →
About The Author
Founder & CEO, Real Estate Skills
Alex Martinez is the Founder and CEO of Real Estate Skills. He has wholesaled and flipped houses for over 14 years, been part of 1,000+ real estate transactions, and personally acquired 55+ residential investment properties. He has trained 6,000+ investors nationwide.
Real Estate Skills is not a law firm or a tax advisory firm, and the information in this article is provided for educational purposes only. It does not constitute legal, tax, or financial advice. Depreciation, passive loss and recapture rules change over time and depend on your income, entity and state. Real estate investing carries risk, and past results do not guarantee future outcomes. Always consult a licensed CPA or tax attorney before claiming bonus depreciation, ordering a cost segregation study, or making any investment decision.
👉FREE Training
How To Consistently Wholesale, Flip Houses, & Invest In Rental Properties From The MLS
(Without Spending $1 On Marketing)

Alex Martinez, the founder of Real Estate Skills, is known for his strong, practical expertise in real estate, starting from a beginner with no family connections in the industry to acquiring over 55 real estate deals, including wholesale and flips, within his first year.
He has dedicated his career to providing cutting-edge education and resources for real estate professionals. He emphasizes the importance of self-taught knowledge through mentors, books, and hands-on experience.
His journey from earning a modest income to becoming a successful real estate entrepreneur and educator showcases his expertise and dedication to the field.

Ryan Zomorodi, co-founder and COO of Real Estate Skills, leverages his experience from a diverse background in real estate investment, construction management, and entrepreneurship to provide comprehensive education in the real estate sector.
His expertise is rooted in hands-on experience, extensive industry knowledge, and a commitment to empowering others through education.
Ryan's journey reflects a blend of practical experience and entrepreneurial success, contributing to his role in developing a platform that educates and supports aspiring real estate professionals.
Read Ryan's Full Bio >>
